Studio Dorighelli
Contact us

STUDIO DORIGHELLI

BUONI BENZINA PER CHI LAVORA LA DOMENICA: QUANDO RIENTRANO NEI FRINGE BENEFIT


L?"Agenzia delle Entrate chiarisce il trattamento fiscale dei benefit riconosciuti ai dipendenti che lavorano ordinariamente la domenica nell?"ambito di un piano di welfare aziendale. Al centro della risposta, le condizioni per l?"applicazione delle regole sui fringe benefit e i limiti di esenzione dal reddito di lavoro dipendente. Con la Risposta n. 189 del 23 ottobre 2026 l?"Agenzia delle Entrate esamina il trattamento fiscale e contributivo dei buoni carburante e dei buoni spesa multiuso che un?"impresa intende riconoscere ai lavoratori impegnati ordinariamente nel servizio domenicale. La società istante, affidataria di servizi pubblici essenziali non interrompibili, intende introdurre per il biennio 2026-2027 un sistema di welfare aziendale destinato al personale che svolge regolarmente attività lavorativa la domenica. I benefit sarebbero erogati mensilmente, sulla base di fasce di appartenenza individuate in funzione dell?"organizzazione del servizio e della frequenza del lavoro domenicale richiesta. L?"iniziativa, secondo quanto rappresentato dalla società, mira a sostenere il benessere dei dipendenti e la conciliazione tra vita personale e lavorativa. Le erogazioni non sarebbero finalizzate a incentivare la performance individuale, né costituirebbero corrispettivi per prestazioni lavorative o premi di produttività o risultato. Il trattamento fiscale dei fringe benefit e la conclusione dell'Agenzia Entrate Nel proprio esame, l?"Agenzia richiama l?"articolo 51 del TUIR, che stabilisce il principio di onnicomprensività del reddito di lavoro dipendente e disciplina, al comma 3, il regime fiscale dei beni e servizi concessi ai lavoratori. Il documento richiama inoltre i chiarimenti di prassi relativi ai buoni carburante e ai voucher, evidenziando che il valore dei beni e dei servizi riconosciuti come fringe benefit deve essere verificato nel rispetto dei limiti previsti dalla normativa applicabile al periodo d?"imposta. Sulla base degli elementi rappresentati dalla società, assunti acriticamente nell?"ambito dell?"interpello, l?"Agenzia ritiene che i buoni carburante e i buoni spesa multiuso previsti dal piano di welfare aziendale rientrino tra i fringe benefitdisciplinati dall?"articolo 51, commi 3 e 3-bis, del TUIR. Di conseguenza, i benefit non concorrono alla formazione del reddito di lavoro dipendente ai fini fiscali e contributivi, entro il limite complessivo previsto dalla normativa vigente nel periodo d?"imposta di riferimento. Fonte: https://www.agenziaentrate.gov.it


People

Meet the team

Request information


You have reached the alowed limit of characters.

Statement on the GDPR (General Data Protection Regulation)

The data controller is Studio Dorighelli, who states that the data acquired in this manner will be handled as follows:

  • it will be used to comply with current requests for information/acquistion/registration until completed and for no other purpose.
  • it will be held in the company archives with no deadline, until independent cancellation by the user, voluntary cancellation by the Controller or an explicit request for cancellation by the user.
  • it will be held on behalf of the Controller by KUMBE, the Controller’s maintainer for digital services, on the cloud server and related backup, in turn managed in compliance with the GDPR for the entire term of the contract with the Controller – who may dispose of it at any time – and until its subsequent cancellation.
  • it will not be assigned to third parties; it will not be used for marketing campaigns except if concurrently authorized for such purposes.
  • the user will have a profile created based pon the information contained therein and the data may be used for statistical processing.
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

Statement on the GDPR (General Data Protection Regulations)

If subscribing to the Newsletter, you must confirm your registration by means of a confirmatory mail sent to the recorded address.  In such case, handling includes:

  • the creation of a group user profile, a status, preferences as indicated and deduced from the information provided in the form and subsequent independent profiles.
  • use of the data for electronic notices (email, whatsapp) and not (paper) for informational/commercial purposes.
  • Use of the email for the creation of marketing campaigns and personallized information, digital and non-digital
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

Dove siamo

Studio Dorighelli
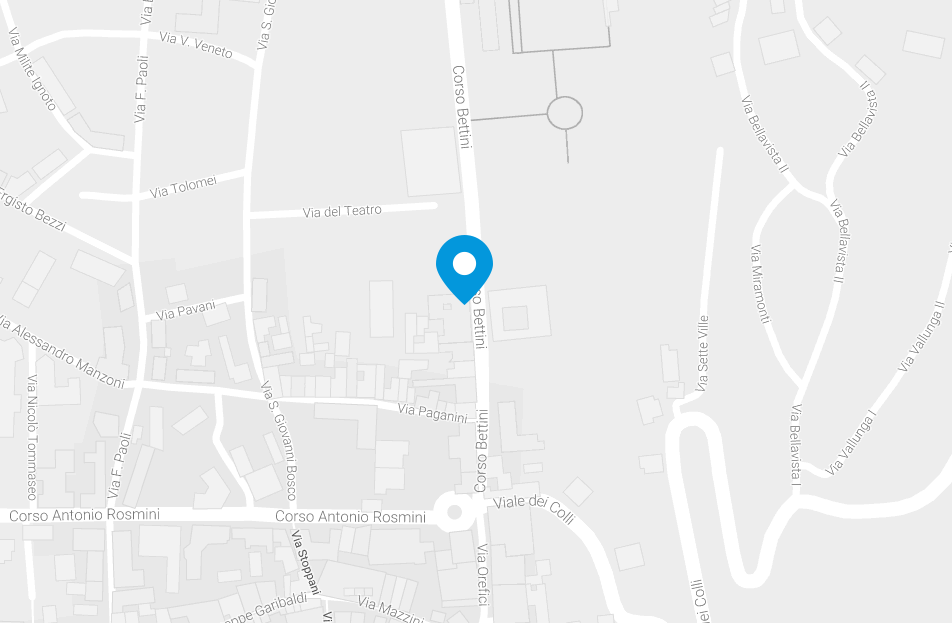
Corso Bettini, 58
38068 Rovereto (TN)
Tel: (+39) 0464 434955
Fax: (+39) 0464 316095
info@studiodorighelli.it
ODC TRENTO

Thanks!

We sent you an email. To activate the newsletter click on the link you will find in the message, thank you!

Iscriviti alla nostra newsletter


Statement on the GDPR (General Data Protection Regulations)

If subscribing to the Newsletter, you must confirm your registration by means of a confirmatory mail sent to the recorded address.  In such case, handling includes:

  • the creation of a group user profile, a status, preferences as indicated and deduced from the information provided in the form and subsequent independent profiles.
  • use of the data for electronic notices (email, whatsapp) and not (paper) for informational/commercial purposes.
  • Use of the email for the creation of marketing campaigns and personallized information, digital and non-digital
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

cancel