Studio Dorighelli
Contact us

STUDIO DORIGHELLI

BONUS PRIMA CASA E ACQUISTO ALL'ESTERO: NIENTE DECADENZA CON LA NUOVA ABITAZIONE PRINCIPALE


Acquistare un nuovo immobile all'estero e rivendere quello agevolato in Italia entro due anni non fa perdere i benefici fiscali. Arrivano i chiarimenti dell'Agenzia delle Entrate sul "cambio casa" transfrontaliero. Con la Risposta n. 200 del 5 novembre 2026 l'Agenzia delle Entrate ha affrontato il caso di un contribuente, cittadino italiano residente all'estero, che aveva acquistato nel 2025 un'abitazione in Italia usufruendo dell'agevolazione "prima casa" con applicazione dell'aliquota IVA ridotta al 4%. Successivamente, il contribuente aveva acquistato un secondo immobile situato all'estero da adibire a propria abitazione principale, pianificando la vendita dell'immobile originariamente agevolato in Italia entro il termine biennale previsto dalla normativa e prima della scadenza del quinquennio. Il quesito posto all'Amministrazione finanziaria mirava a chiarire se il combinato disposto dei commi 4 e 4-bis della Nota II-bis all'articolo 1 della Tariffa, Parte prima, allegata al TUR – come modificato dalla legge n. 207/2024 che ha innalzato a due anni il termine per la rivendita – consentisse di evitare la decadenza dall'agevolazione "prima casa" anche nell'ipotesi in cui l'immobile acquistato successivamente si trovi all'estero anziché in Italia. Le conclusioni dell'Agenzia delle Entrate: validità del beneficio con l'immobile estero L'Agenzia delle Entrate ha chiarito che "una lettura logico-sistematica dei commi 4 e 4-bis della Nota II-bis" consente di conservare il beneficio fiscale fruito per il primo acquisto anche quando il nuovo immobile destinato ad abitazione principale si trova all'estero, purché si proceda alla vendita dell'immobile agevolato preposseduto in Italia nel termine di due anni dal secondo acquisto. Di conseguenza, il contribuente non decade dall'agevolazione "prima casa" italiana a condizione che l'immobile acquistato all'estero venga effettivamente adibito a "dimora abituale" entro il termine biennale.  Al momento della rivendita entro il quinquennio dell'unità in Italia, concludono le Entrate, il contribuente dovrà presentare all'ufficio competente la documentazione idonea a comprovare l'acquisto all'estero (copia del rogito) e la destinazione a dimora abituale (quali le fatture di fornitura di luce, acqua o gas), munite di apostille e tradotte in lingua italiana in conformità alla Convenzione dell'Aja del 5 ottobre 1961. Fonte: https://www.agenziaentrate.gov.it

People

Meet the team

Request information


You have reached the alowed limit of characters.

Statement on the GDPR (General Data Protection Regulation)

The data controller is Studio Dorighelli, who states that the data acquired in this manner will be handled as follows:

  • it will be used to comply with current requests for information/acquistion/registration until completed and for no other purpose.
  • it will be held in the company archives with no deadline, until independent cancellation by the user, voluntary cancellation by the Controller or an explicit request for cancellation by the user.
  • it will be held on behalf of the Controller by KUMBE, the Controller’s maintainer for digital services, on the cloud server and related backup, in turn managed in compliance with the GDPR for the entire term of the contract with the Controller – who may dispose of it at any time – and until its subsequent cancellation.
  • it will not be assigned to third parties; it will not be used for marketing campaigns except if concurrently authorized for such purposes.
  • the user will have a profile created based pon the information contained therein and the data may be used for statistical processing.
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

Statement on the GDPR (General Data Protection Regulations)

If subscribing to the Newsletter, you must confirm your registration by means of a confirmatory mail sent to the recorded address.  In such case, handling includes:

  • the creation of a group user profile, a status, preferences as indicated and deduced from the information provided in the form and subsequent independent profiles.
  • use of the data for electronic notices (email, whatsapp) and not (paper) for informational/commercial purposes.
  • Use of the email for the creation of marketing campaigns and personallized information, digital and non-digital
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

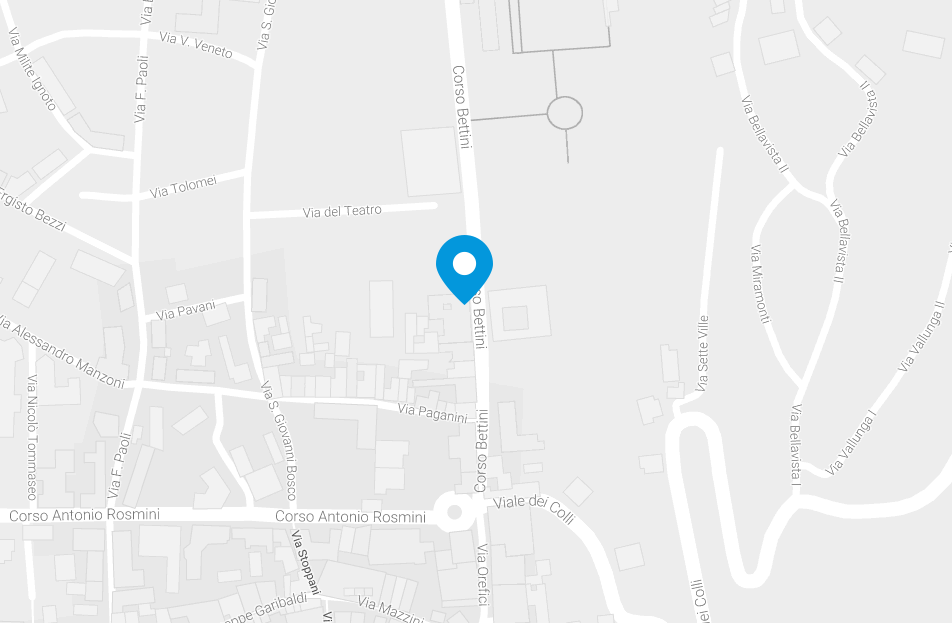
Dove siamo

Studio Dorighelli
Corso Bettini, 58
38068 Rovereto (TN)
Tel: (+39) 0464 434955
Fax: (+39) 0464 316095
info@studiodorighelli.it

ODC TRENTO

Thanks!

We sent you an email. To activate the newsletter click on the link you will find in the message, thank you!

Iscriviti alla nostra newsletter


Statement on the GDPR (General Data Protection Regulations)

If subscribing to the Newsletter, you must confirm your registration by means of a confirmatory mail sent to the recorded address.  In such case, handling includes:

  • the creation of a group user profile, a status, preferences as indicated and deduced from the information provided in the form and subsequent independent profiles.
  • use of the data for electronic notices (email, whatsapp) and not (paper) for informational/commercial purposes.
  • Use of the email for the creation of marketing campaigns and personallized information, digital and non-digital
  • the complete privacy policy may be found at the link www.studiodorighelli.it/privacy. For information or requests, you may write to the following electronic mail address: info@studiodorighelli.it.

cancel